

Financial inclusion advocates warn that regulation without clear national policy creates operational uncertainties for institutions serving vulnerable populations.
Ghana Association of Financial Non-Governmental Organisations Chairman Spencer Badu has urged the government to expedite passage of the National Microfinance Policy, warning that years of delay have left the sector in a precarious position as regulation has preceded policy formulation.
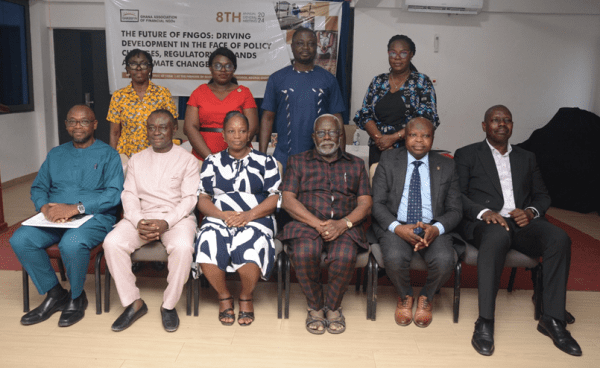
Speaking at GHASSFIN’s eighth Annual General Meeting and symposium, Badu emphasized the urgency of establishing clear policy guidelines for the microfinance sector, which serves as a critical gateway to financial inclusion for rural and low-income communities across Ghana.
“Let government, let the central bank, let the Ministry of Finance prioritise the policy and ensure there’s a policy that spells out clearly what microfinance is,” Badu stated during the event, highlighting the institutional confusion created by the current regulatory-first approach.
The 18-member association, comprising financial non-governmental organizations operating across Ghana, faces mounting pressure from uniform regulatory requirements that fail to account for institutional capacity differences. GHASSFIN successfully advocated for a reduced minimum capital requirement of GH¢300,000 for its members, compared to the GH¢2 million demanded from other microfinance institutions.
However, Badu argues that even this lower threshold remains prohibitive for smaller community-based organizations that often begin as faith-based or passion-driven initiatives. The chairman advocates for a tiered regulatory system where the Bank of Ghana maintains oversight while partnering with GHASSFIN to monitor smaller institutions.
“The big ones have the capital and capacity to meet regulatory requirements, but those that are local need hand-holding,” Badu explained, proposing a framework that allows smaller institutions to “grow gradually to become big entities.”
Beyond regulatory concerns, Badu called for the establishment of a dedicated Microfinance Fund to support institutions serving Ghana’s most vulnerable populations. He questioned the sustainability of current approaches, noting that handouts from NGOs and government have proven insufficient for long-term impact.
The microfinance sector’s challenges extend to climate-related risks, particularly in agriculture where recent droughts in northern Ghana led to widespread crop failures and mass loan defaults. Badu emphasized the need for stronger collaboration with insurance providers to de-risk agricultural lending and protect both lenders and borrowers from climate-induced losses.
Without access to formal microfinance services, farmers and other vulnerable borrowers often resort to middlemen who offer loans in exchange for future harvests, creating what Badu described as a “permanent cycle of debt” with interest rates exceeding 100 percent.
The policy vacuum has broader implications for Ghana’s poverty reduction efforts. Badu positioned microfinance as essential infrastructure for economic development, noting that the majority of Ghanaians operate at the economic level served by these institutions.
“If we want to mitigate poverty, move people out of the poverty line, then we need to support these institutions,” he emphasized, arguing that sustainable poverty reduction requires “supporting institutions in capacity and in resources” rather than direct handouts.
The timing of GHASSFIN’s appeals coincides with broader financial sector reforms in Ghana, where authorities are balancing regulatory oversight with the need to expand financial inclusion. The Bank of Ghana has implemented various capital requirements across different tiers of financial institutions, but critics argue the approach lacks the nuanced understanding needed for microfinance operations.
Badu’s call for a comprehensive National Microfinance Policy reflects growing recognition that effective regulation requires clear policy foundations. The proposed framework would establish definitions, operational guidelines, and support mechanisms for institutions serving populations often excluded from traditional banking services.
The microfinance sector’s advocacy efforts highlight the tension between ensuring financial stability through regulation and maintaining accessibility for institutions serving Ghana’s most economically vulnerable communities.

