

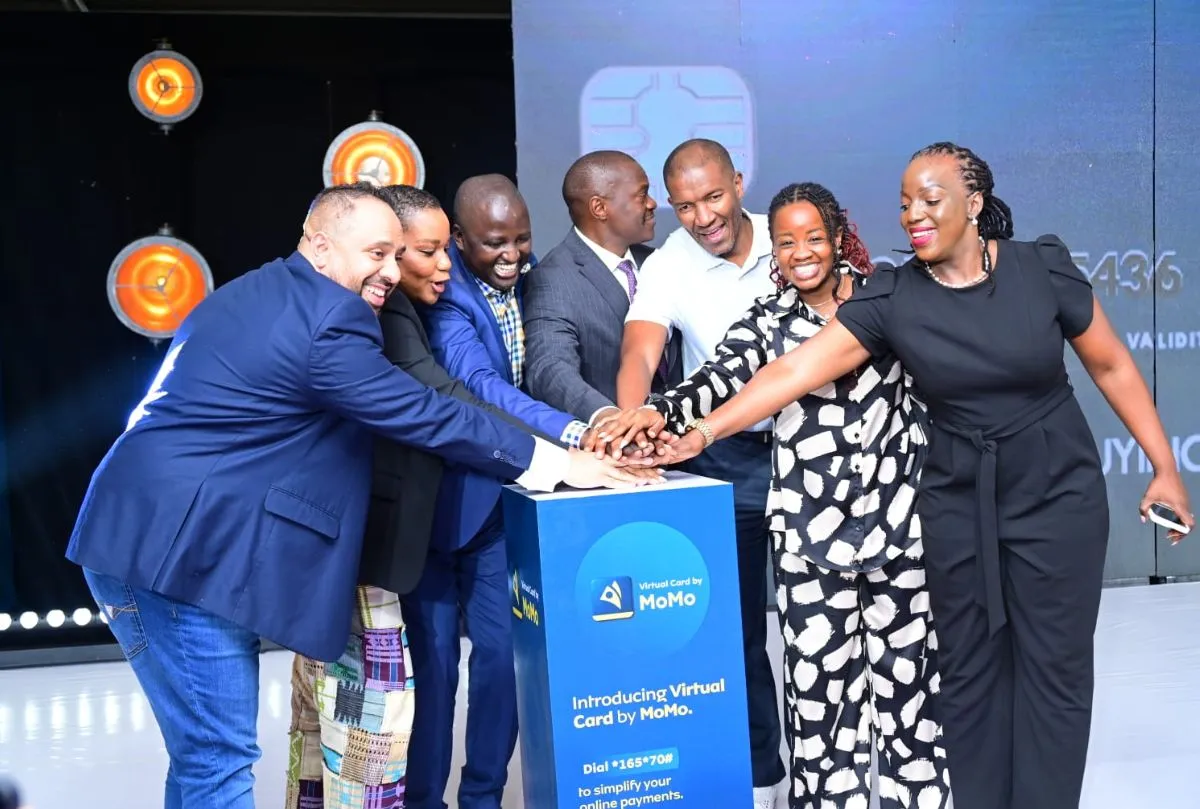
In a bold stride toward financial inclusivity, MTN Mobile Money Uganda has launched the Virtual Card by MoMo—a digital payment tool enabling millions of Ugandans to transact online without physical cards or traditional bank accounts.
Developed in partnership with Mastercard, Diamond Trust Bank, and Network International, the innovation aims to deepen Uganda’s integration into the global digital economy while addressing longstanding barriers to financial access.
The move comes amid surging mobile money activity in Uganda, where transactions hit Shs 191 trillion (GH¢805.2 billion) between July 2022 and June 2023, a 23% year-on-year jump, per Bank of Uganda data. The virtual card, linked directly to users’ MoMo wallets, allows payments on global platforms like Amazon, Netflix, and Airbnb, as well as local services such as Jumia and Market by MoMo. Students can pay school fees online, entrepreneurs can fund social media ads, and travelers can book flights—all without a bank intermediary.
“This isn’t just a product; it’s a gateway to economic participation,” said Jemima Kariuki Njuguna, MTN MoMo’s Chief Product Officer. She tied the launch to MTN’s Ambition 2025, which prioritizes leveraging mobile networks to bridge Africa’s financial divide. Mastercard’s Muhammad Nana echoed this, highlighting the card’s potential to “democratize access” for Uganda’s unbanked majority, estimated at 36% of adults.
Simplicity Meets Security
Users can activate the virtual card via USSD code 16570#, bypassing paperwork. Transactions are secured with Mastercard’s anti-fraud protocols, while a “top-up-as-you-go” feature lets customers load only necessary funds, curbing overspending risks. The card also unlocks exclusive deals, such as discounted airfares, enhancing its appeal.
While the rollout signals progress, hurdles persist. Uganda’s internet penetration lags at 30%, and digital literacy gaps may slow adoption among rural populations. Moreover, the service’s success hinges on consistent electricity and network stability—variables not yet guaranteed nationwide.
Analysts note the innovation could pressure traditional banks to accelerate digital offerings, fostering competition. “This blurs the line between telecoms and banking,” said Kampala-based fintech expert Paul Mugambi. “It’s a win for consumers but challenges regulators to keep pace with hybrid financial models.”
The Virtual Card arrives as Uganda’s government pushes cashless transactions to curb tax evasion and formalize the informal sector, which constitutes 53% of GDP. However, concerns linger over transaction fees and merchant acceptance rates, critical factors for low-income users.
If successful, the Virtual Card could set a template for neighboring markets, where mobile money dominance coexists with low bank-account ownership. For now, its impact will depend on MTN’s ability to educate users and scale infrastructure—a test case for Africa’s broader digital finance ambitions.
As Uganda navigates this transition, the Virtual Card by MoMo underscores a pivotal truth: in economies leapfrogging traditional banking, innovation must balance aspiration with accessibility. The stakes are high, but so too are the rewards.

